Sinking funds are small savings pots for costs you know are coming. Instead of a big bill wrecking your budget, you save a little each month so the money is already there when it is due.
They are one of the simplest money habits there is, and they stop the cycle of putting holidays, car repairs and birthdays on a credit card.
What are sinking funds?
A sinking fund is money you set aside on purpose for one future expense. It is different from an emergency fund. An emergency fund covers surprises like a job loss. Sinking funds cover costs you can predict, even if you do not know the exact date.
How to set up sinking funds
- List the costs you know are coming in the next 12 months, such as holidays, car insurance, school supplies and birthdays.
- Estimate how much each one will cost. Last year's bank statements are a great place to look.
- Count the months until each one is due.
- Divide the cost by the number of months. That is your monthly amount for each sinking fund.
- Move the money on payday, ideally with an automatic transfer.
Sinking funds examples
| Sinking fund | Cost | Months away | Save each month |
|---|---|---|---|
| Holiday gifts and food | $600 | 6 | $100 |
| Car insurance renewal | $540 | 9 | $60 |
| Back to school | $300 | 10 | $30 |
| Birthdays | $240 | 12 | $20 |
| Car repairs and tires | $480 | 12 | $40 |
In this example, five sinking funds cost $250 a month. That feels much easier than finding $2,160 when the bills arrive.
Where to keep sinking funds
- A high yield savings account with separate buckets or nicknames for each goal.
- One savings account with a simple spreadsheet that tracks each fund.
- Cash envelopes for small, frequent costs like birthday gifts.
Start with just one or two sinking funds for your biggest yearly costs. Add more once saving for them becomes a habit.
A grocery sinking fund
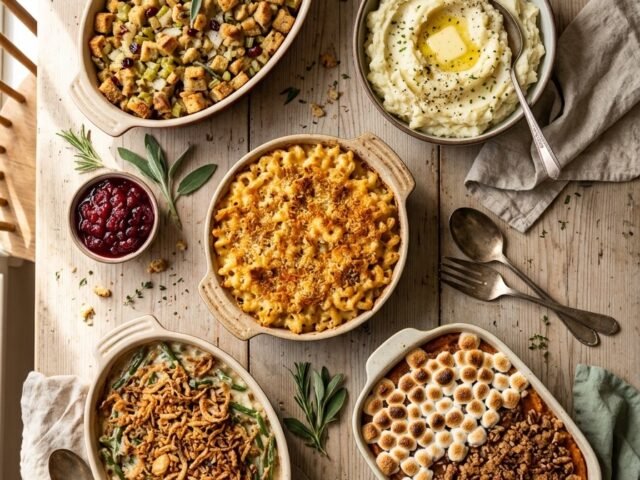
Food costs can jump around the holidays. A small grocery sinking fund pays for Thanksgiving dinner and pantry stock ups without blowing your weekly budget. Pair it with our grocery budget for a family of 4 and our $50 weekly meal plan.
For free, trustworthy money basics, the federal MyMoney.gov site has simple guides on saving and spending.
Common categories to save for
- Holidays and gifts: the biggest surprise cost for most families each year.
- Car costs: insurance renewals, registration, new tires and routine repairs.
- Home repairs: a broken appliance or a plumber visit.
- Medical and dental: deductibles, glasses and prescriptions.
- Back to school: clothes, shoes and supplies each August.
- Annual subscriptions: memberships and software that renew once a year.
- Pets: vet visits, vaccines and grooming.
- Travel: a summer trip or visiting family.
How they fit into your budget
Treat each monthly amount like a bill. When you make your monthly budget, list your savings pots right after rent and utilities, so the money is set aside before it can be spent. If money is tight, start with the costs that would otherwise go on a credit card, since interest makes those the most expensive.
Mistakes to avoid
- Guessing the cost too low. Round up so you are not caught short.
- Mixing the money with your checking account, where it is easy to spend.
- Starting too many pots at once and giving up when it feels like too much.
- Forgetting to adjust after a cost goes up, like a new insurance rate.
Frequently asked questions about sinking funds
How many sinking funds should I have?
Start with two or three for your biggest predictable costs, then add more as your budget allows.
Are sinking funds the same as an emergency fund?
No. Sinking funds are for costs you can plan for. An emergency fund is for true surprises.
What if I need the money early?
Use it for its purpose, then adjust the monthly amount to catch up before the next due date.
Do sinking funds work on a small income?
Yes. Even $10 a month into one fund means less stress when the bill arrives.




1 comment